Life Coach Insurance: What It Covers and What It Costs
life coach insurance: compare liability options, current insurer price examples, the questions to ask before buying, and the records to have ready.
By Life Coaching Kit by Cosmo Suite · Editorial policy
Published · 10 min read
Your first coaching client has booked. The agreement is ready, and now you are deciding whether to buy insurance before session one. That choice depends on your work and location. Describe your practice, then ask an agent which coverage may fit.
“Life coach insurance” can mean several policies. Professional liability, general liability, and a business owner’s policy each cover different risks. Prices vary by insurer and practice, too. Here are the common terms, published price examples, and questions to take to a licensed agent.
General information, not legal or insurance advice. Check with a licensed adviser.
If the client paperwork is still coming together, a ready-made set of life coaching templates can help you organize the forms before your first session.
Key takeaways:
- Insurance is a group of coverage types, not one standard policy for every coach.
- Professional liability and general liability address different kinds of claims; a BOP may combine general liability with property coverage.
- Published premiums are examples, not personal quotes. Compare the policy terms and exclusions as well as the price.
- A short practice snapshot makes it easier to ask an agent specific questions.
Life coach insurance covers different kinds of risk
Life coach insurance may include several types of coverage, each tied to a different risk. The U.S. Small Business Administration describes professional liability as coverage for service-related claims and general liability as coverage for certain injury or property claims. The policy wording decides what applies to your practice.
| Risk areas to discuss | What the illustration represents |
|---|---|
 |
The work itself, where you meet clients, and the equipment you use raise different questions for an insurer. The image is illustrative, not a map of guaranteed coverage. |
Professional liability is coverage for claims about a service, mistakes, or negligence. General liability is coverage for certain third-party injury or property claims. A business owner’s policy (BOP) is a package that often combines general liability with business property and income cover. The exact scope and exclusions come from the policy.
For example, a client might complain about your service. A visitor getting hurt in a rented room raises a different risk. So does damage to a laptop in a covered event. Whether a policy responds depends on its terms.
The SBA says insurance can fill gaps alongside a business structure, and rules vary by state. It advises business owners to assess risks, speak with a licensed agent, and compare terms and prices. Use those steps to start a conversation; they do not establish what every coach must buy.
If a client has asked what they will sign and receive, this guide to coaching forms by client stage maps the paperwork side of your practice. Forms record the coaching relationship. Insurance questions depend on the policy between you and the insurer.
Life Coach Insurance: What to Use When
Your work, location, and possible losses shape the conversation with an agent. Use the table to frame it. The last column gives situations to ask about; it does not recommend or require a policy.
| Coverage label | Common purpose | Ask about it when |
|---|---|---|
| Professional liability | Claims connected to professional services, errors, or negligence | A client pays for your coaching guidance or you provide a defined service |
| General liability | Certain third-party injury or property-damage claims | You meet clients in person, rent rooms, or host workshops |
| Business owner’s policy (BOP) | Often bundles general liability with business property coverage; details vary | You want to ask about both third-party claims and your business equipment or space |
| Employee-related cover | May apply when you hire staff; rules and policy needs vary by location | You add an employee or change how people work for your business |
The SBA guide to business insurance describes professional liability as relevant to businesses that provide services. The Hartford and Hiscox describe life-coach policies that include professional liability options. A BOP may leave professional liability separate. The Hartford’s BOP guide says its BOP combines general liability, commercial property, and business income coverage. Check the offer you receive to see whether professional liability is included or separate.
| Business information | Client paperwork |
|---|---|
 |
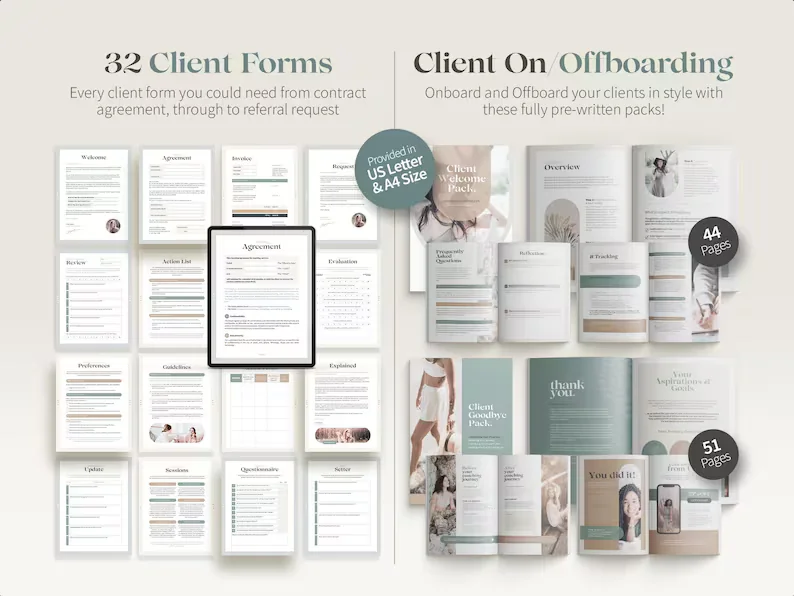 |
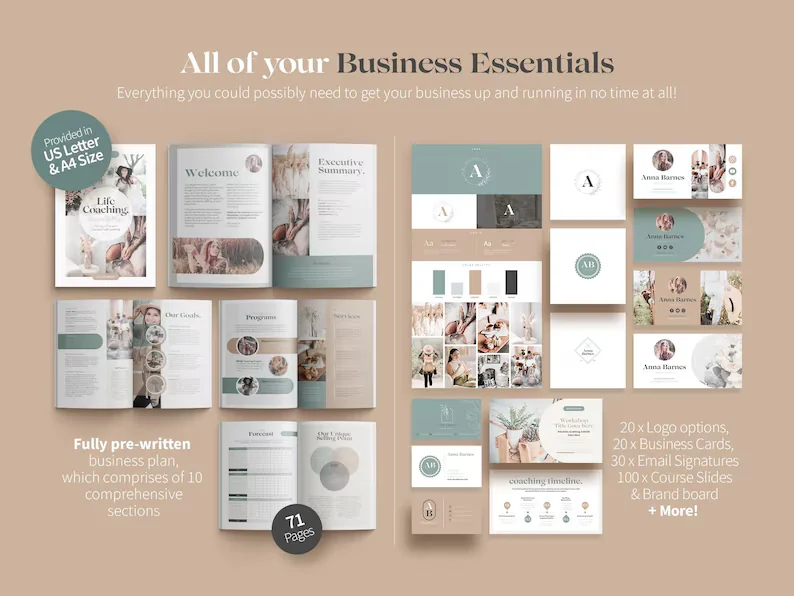
These screenshots show real Life Coaching Kit pages. The business essentials page can help you document services and prices. The client forms page shows the paperwork clients see. They do not serve as an insurance application, policy, or proof of cover. The full set of coaching templates includes business and client paperwork in one editable collection.
What life coach insurance costs in current examples
These price examples were checked on 14 October 2026. Hiscox lists starting or “as little as” monthly prices on its life coach page. The Hartford’s page, last updated 9 April 2025, reports average prices paid by its small-business insurance customers. Neither source gives a quote for your practice.
| Insurer and coverage | Published price | What the figure means |
|---|---|---|
| Hiscox professional liability | Starts at $22.50/month, or $270 for 12 months at that monthly rate | A starting price, not a quote |
| Hiscox general liability | As little as $30/month, or $360 for 12 months at that monthly rate | A “starting low” figure, not a quote |
| Hiscox BOP | As low as $42/month, or $504 for 12 months at that monthly rate | A “starting low” figure, not a quote |
| The Hartford BOP | $686/year, about $57/month | Average paid by its small-business customers |
| The Hartford standalone general liability | $464/year, about $39/month | Average paid by its small-business customers |
| The Hartford workers’ compensation | $524/year, about $44/month | Average paid by its small-business customers |
For Hiscox, the annual figures multiply each monthly price by 12. For The Hartford, the monthly amounts divide each annual figure by 12. These calculations help compare the examples, but they are not quotes. Starting prices and customer averages measure different things.
The Hartford says its figures are small-business customer averages, not life-coach quotes. Costs vary with the business and insurer rating factors. Hiscox says a coach’s price can depend on risk, claims history, and coverage type. Request a quote from each insurer using the same practice details. Compare limits, deductibles, exclusions, payment terms, and the policy’s definition of covered services.
Match a quote to your actual practice
Before asking about coverage, give the agent a short, accurate description of your practice. Say what you do, where and how you meet, what property you use, and whether anyone works for you. If these details change, ask if the insurer needs an update.
| Practice detail | Write down | Why the agent needs it |
|---|---|---|
| Services | One-to-one life coaching, group sessions, workshops, or other work | The insurer can confirm which activities it considers covered |
| Delivery and locations | Online or in person; where you work and where clients are located | The agent can explain any location or delivery limits |
| Space and equipment | Home office, rented room, laptop, or other business property | Helps frame questions about property and premises risks |
| People involved | Solo, employee, or contractor; what each person does | Hiring or changing roles can affect what to ask about |
| Quote preparation | What to check |
|---|---|
 |
Keep each detail short and factual. Bring the same snapshot to every quote conversation so you can compare the answers. |
For instance, if you also offer therapy, health services, financial guidance, or another service, describe each one separately and ask if it falls within the policy. Keep this factual. A “coach” label may not include every service you provide. The insurer can tell you what it covers and what it excludes.
Your client agreement and service list can help you keep the description consistent. The clause-by-clause coaching agreement guide explains the service and role boundaries to document. Have the final agreement reviewed for your location. It should describe the coaching arrangement accurately. It cannot promise an insurance result.
Six questions to ask before you buy
Ask the agent to answer these questions against the policy documents. You need to know what work is covered, which situations are outside the policy, and what to update when your practice changes. Save the answers with each quote so you can compare them later.
- Are my listed services covered? Give the agent your practice snapshot. Ask about each service separately, including workshops or group work.
- Does the policy include professional liability? If the quote is for a BOP, ask whether service-related claims need a separate policy or endorsement.
- Are online sessions and my client locations covered? Share where you and your clients are based. Ask how the policy handles cross-border work and get the answer in writing.
- What are the limits, deductible, and exclusions? Ask what the policy pays toward a covered claim, what you pay first, and which activities or events are excluded.
- When does the policy respond, and how long do I have to report a claim? Ask the agent to explain the policy’s trigger and reporting terms in plain language.
- What should I report if my practice changes? Ask about new services, employees, rented spaces, or workshops, and what proof of insurance a client or venue can request.
The SBA recommends comparing terms and prices and working with a licensed agent. Read the full policy, including its definitions and exclusions, and get advice for your circumstances.
Keep a small paper trail for your policy
Keep the quote, policy, declarations page, any certificate, and renewal messages together. Add the practice snapshot you gave the agent. Date a note when you add a service or change your workspace. This record shows what details the insurer received and what may need an update at renewal.
Keep insurance records apart from client files. Your agreement, intake form, and session notes contain different information and serve different purposes. A coaching agreement does not set your insurance coverage. A certificate also does not replace the full policy. Store each document in the right place and limit access to people who need it. If you want the client paperwork in one matching set, see the editable forms and business templates.
| Keep records separate | What belongs there |
|---|---|
 |
Client forms and coaching notes belong with client records. Quotes, policy documents, and renewal notes belong with business records. |
The paperwork you send to clients should match the service you described to an insurer. The policy is a separate contract between you and the insurer.
Where the Life Coaching Kit Fits
If your next task is getting the client paperwork in order, the Life Coaching Kit includes a coaching agreement, intake forms, an onboarding questionnaire, a welcome pack, a services and pricing guide, and invoice templates. The files are editable in Canva. They are not insurance, legal advice, or booking and payment software.
The kit organizes client documents and the service details you share. For insurance choices or coverage questions, ask a licensed adviser. Have an agreement reviewed for your location. See the client paperwork and business templates in the Life Coaching Kit before deciding whether its editable documents suit your practice.
How we put this together. We are the Cosmo Suite team that sells the Life Coaching Kit. We checked the U.S. Small Business Administration and insurer pages on 14 October 2026; The Hartford page is dated 9 April 2025. The prices are the insurers’ own descriptions. They are not quotes and do not compare equivalent policies. Read about us and our contact details and our editorial policy. This is general information, not legal or insurance advice.
Frequently Asked Questions
Do life coaches need insurance?
Requirements depend on where you work, your business setup, whether you have employees, and any contract terms that apply. Insurance rules can vary by state. Ask a licensed insurance adviser to check which requirements apply to your practice before you buy.
What insurance does a life coach need?
Start with the service and the risks you want to discuss. Professional liability may relate to claims about your service; general liability relates to certain injury or property claims. A BOP often combines general liability and property coverage. Ask an agent which options fit your work, then read the policy exclusions.
How much does life coach insurance cost?
Hiscox lists professional liability starting at $22.50 per month and a BOP as low as $42 per month. The Hartford reports a $686 annual BOP average for its small-business customers. These are different kinds of price examples, checked on 14 October 2026, and neither predicts your quote.
Does professional liability insurance cover online coaching?
Coverage depends on the policy wording and the locations of you and your clients. Tell the insurer where each side is based, how sessions happen, and which services you provide. Ask the agent to confirm location limits and exclusions in writing before you rely on the policy.
Is a BOP the same as professional liability insurance?
No. A BOP often bundles general liability with business property and business income coverage. Professional liability covers a different category of service-related claims and may need to be added separately. The bundle depends on the insurer, so compare the policy documents with the label on the quote.
Does a coaching agreement replace insurance?
No. An agreement records the working relationship and its terms. Insurance is a contract with an insurer, and its wording sets which claims may be covered. Keep the documents separate. Have your coaching agreement reviewed for your location.
Frequently asked questions
Do life coaches need insurance?
Requirements depend on where you work, your business setup, whether you have employees, and any contract terms that apply. Insurance rules can vary by state. Ask a licensed insurance adviser to check which requirements apply to your practice before you buy.
What insurance does a life coach need?
Start with the service and the risks you want to discuss. Professional liability may relate to claims about your service; general liability relates to certain injury or property claims. A BOP often combines general liability and property coverage. Ask an agent which options fit your work, then read the policy exclusions.
How much does life coach insurance cost?
Hiscox lists professional liability starting at $22.50 per month and a BOP as low as $42 per month. The Hartford reports a $686 annual BOP average for its small-business customers. These are different kinds of price examples, checked on 14 October 2026, and neither predicts your quote.
Does professional liability insurance cover online coaching?
Coverage depends on the policy wording and the locations of you and your clients. Tell the insurer where each side is based, how sessions happen, and which services you provide. Ask the agent to confirm location limits and exclusions in writing before you rely on the policy.
Is a BOP the same as professional liability insurance?
No. A BOP often bundles general liability with business property and business income coverage. Professional liability covers a different category of service-related claims and may need to be added separately. The bundle depends on the insurer, so compare the policy documents with the label on the quote.
Does a coaching agreement replace insurance?
No. An agreement records the working relationship and its terms. Insurance is a contract with an insurer, and its wording sets which claims may be covered. Keep the documents separate. Have your coaching agreement reviewed for your location.